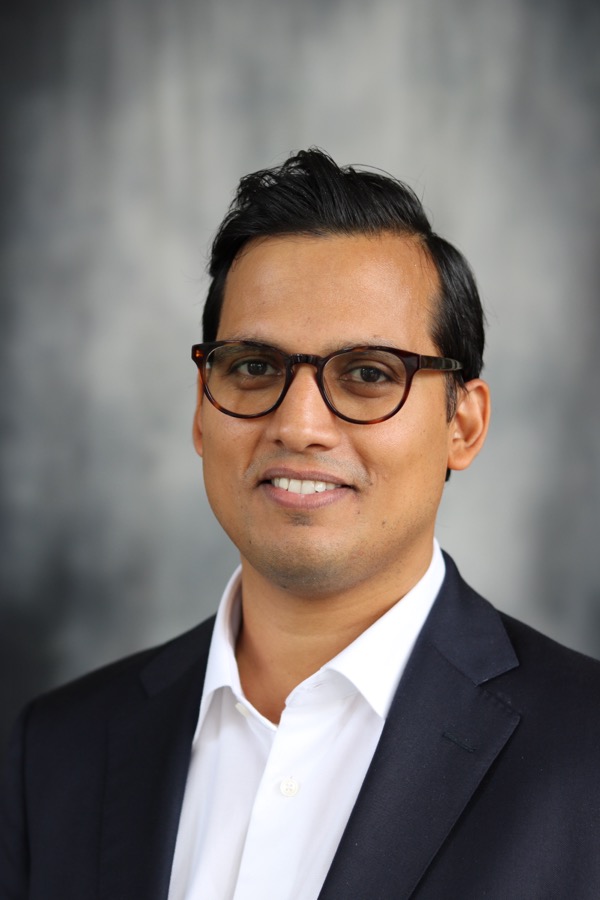
Vivek Pandey

Vivek Pandey

Assistant Professor of AccountingSimon Business SchoolUniversity of Rochester

My research centers on empirical accounting and often intersects with political economy and labor economics. I study how regulation, politics, and disclosure shape individuals, firms, institutions, and markets.

Before joining the University of Rochester in 2022, I earned a Ph.D. from the University of Southern California.

vpandey4@simon.rochester.edu

Research

Published and accepted papers

Independence at What Cost? Regulation, Accounting Careers, and Human Capital

With Xingyu Shen, Joanna Wu, and Xixi Xiao

Journal of Accounting and Economics, 2026, 101916

Winner, 2026 FARS Connecting to Practice Award

Presented at the 2025 Journal of Accounting and Economics Conference

Abstract: Independence at What Cost? Regulation, Accounting Careers, and Human Capital

On-the-job training is a key driver of human capital development (Becker, 1962). We argue that the Sarbanes-Oxley Act (SOX), aimed at strengthening auditor independence, changed the economics of public accounting and unintentionally reduced opportunities for accountants to invest in their human capital on the job. SOX barred public accounting firms from offering consulting services to audit clients and introduced barriers to accountants transitioning to client firms. This weakened opportunities for collaboration between audit and consulting, limited accountants’ exposure to addressing clients’ business problems, and reduced networking. This diminished opportunities for accountants to gain broad experience, develop skills, and grow professional networks, making the accounting profession less attractive, especially to top talent. Using individual-level data, we compare accountants (treated group) and consultants (benchmark group) before and after SOX, within the same public accounting firm, time, and location. After SOX, accountants were less likely to move into consulting roles or to clients of their audit firms, and their wages declined. Consistent with reduced career opportunities discouraging accounting education, we find a drop in the quality of students declaring accounting majors after SOX. Importantly, to more directly connect career opportunities to university accounting enrollments, we show that when university alumni transitions from public accounting to consulting decline, both the quantity and quality of subsequent accounting enrollments at their alma maters drop. We uncover a previously overlooked cost of regulations concerning the accounting profession.

Select conferences: 2025 Journal of Accounting and Economics Conference; 2025 NYU Big Apple Accounting Conference

Partisanship, Information, and Punishment for Misconduct at Work

With Joanna Wu and Yuanzhe Zhang

Journal of Accounting Research, 2026

Abstract: Partisanship, Information, and Punishment for Misconduct at Work

We examine whether firms apply partisan standards when responding to employee financial misconduct. Using detailed individual-level data on financial advisers, we find that advisers who are in the political minority at their firm (political minority advisers) are no different from their colleagues at the same firm and time in the incidence and severity of misconduct, yet following misconduct, they are significantly more likely to depart—a pattern we term “partisan punishment standards.” This pattern is especially pronounced at firms with lower internal information quality, proxied with (1) lower external reporting quality (for public firms only), (2) private firms (relative to public firms), and (3) not hiring an independent public accountant to create an internal control report (for both public and private firms). We also document “partisan reporting standards”: firms are more likely to publicly disclose misconduct by political minority advisers while remaining relatively silent in other cases. Firms that exhibit partisan punishment practices subsequently experience slower growth.

Select conferences: 2026 Dartmouth Accounting Winter Conference; 2026 Bocconi Accounting Symposium; 2025 HKUST Accounting Research Symposium

Contractual Private Disclosures in Supply Chains and Managerial Learning from Financial Markets

Sole-authored

The Accounting Review, 2026, 101(5), 411–443

Abstract: Contractual Private Disclosures in Supply Chains and Managerial Learning from Financial Markets

I examine whether contracts that require customers to privately share with suppliers forecasts of their future demand for the supplier’s products (“demand forecast contracts,” or “DF contracts”) affect the supplier’s reliance on an alternative information source—stock prices—when making investment decisions. If suppliers find these forecasts a more direct signal of future demand than stock prices, they may reduce their reliance on stock prices to guide investments. Using hand-collected data, I find that suppliers’ investments become significantly less sensitive to stock prices after entering a DF contract for the first time. This effect is stronger when forecasts are more credible, demand more uncertain, and investments more irreversible. Supplier performance, measured by return on assets and cash flow from operations, improves post-DF. Overall, these findings suggest that when a relatively direct information source about future demand becomes available, managers reduce their reliance on stock prices in making real decisions.

Partisan Regulatory Actions: Evidence from the SEC

With Xingyu Shen and Joanna Wu

Journal of Accounting and Economics, 2025, 80(1), 101777

Cited in Cato Institute amicus briefs before the U.S. Supreme Court (Sripetch v. SEC, No. 25-466)

Abstract: Partisan Regulatory Actions: Evidence from the SEC

We study the influence of political partisanship in SEC investigations and AAER enforcement actions against financial misconduct. We find that the SEC is more likely to launch an investigation against a firm that is misaligned with the agency’s political ideology than other firms. The likelihood of an AAER appears unaffected by political misalignment, but once named in an AAER, a misaligned firm faces harsher penalties than other firms. We find evidence that collectively points to potential misallocation of scarce enforcement resources due to partisanship: conditional on investigation, misaligned firms are less likely to receive an enforcement action, and conditional on misreporting, non-misaligned firms are less likely to be investigated.

Select conferences: 2024 London Business School Accounting Symposium

Client Concerns About Information Spillovers From Sharing Audit Partners

With Jung Koo Kang and Clive Lennox

Journal of Accounting and Economics, 2022, 73(1), 101434

Abstract: Client Concerns About Information Spillovers From Sharing Audit Partners

We hypothesize that companies in the same product market avoid sharing the same audit partner when they are concerned about possible information spillovers. Consistent with our hypothesis, we find that product market rivals are less likely to share the same partner when they perceive that information spillovers are more costly. While concerns about information spillovers significantly reduce the likelihood of product market rivals sharing the same audit partner, we find that such concerns do not deter them from sharing the same audit office. Lastly, when companies are unconcerned with information spillovers, our results suggest that partner sharing can be beneficial because it can result in lower audit fees and fewer accounting misstatements.

Select conferences: 2019 PCAOB/TAR Conference on Auditing and Capital Markets

Shareholder Litigation and Conservative Accounting: Evidence from Universal Demand Laws

With Hariom Manchiraju and K.R. Subramanyam

The Accounting Review, 2021, 96(2), 391–412

Abstract: Shareholder Litigation and Conservative Accounting: Evidence from Universal Demand Laws

We use the staggered adoption of the Universal Demand Laws (UD Laws) to examine the effect of an exogenous reduction in shareholders’ ability to litigate on the extent of accounting conservatism. On average, we find an increase in reporting conservatism post-UD. The increased conservatism is concentrated in firms that contemplate equity issuance, with a high proportion of monitoring investors, and high corporate governance quality. In contrast, firms with specific short-term incentives for aggressive accounting—such as those narrowly beating benchmarks, those with abnormal insider trading, and those likely to violate debt covenants—weakly governed firms, and firms with high ex ante litigation risk decrease reporting conservatism after UD. Our results suggest that the relation between the litigation environment and reporting conservatism is complex and dependent on specific characteristics and unique circumstances of the firms.

Working papers

Tenure Contracts and Human Capital Allocation

With Xingyu Shen, Joanna Wu, and Xixi Xiao

Revise and resubmit, Management Science

Independence Regulations of the Accounting Profession Around the Globe and Accountants’ Human Capital

With Joanna Wu, Xixi Xiao, and Yuanzhe Zhang

Immigrant CEOs and Regulatory Scrutiny in America: Evidence from the SEC

With Xingyu Shen and Joanna Wu